Understanding Mortgage Rates in Orange County, CA This Year
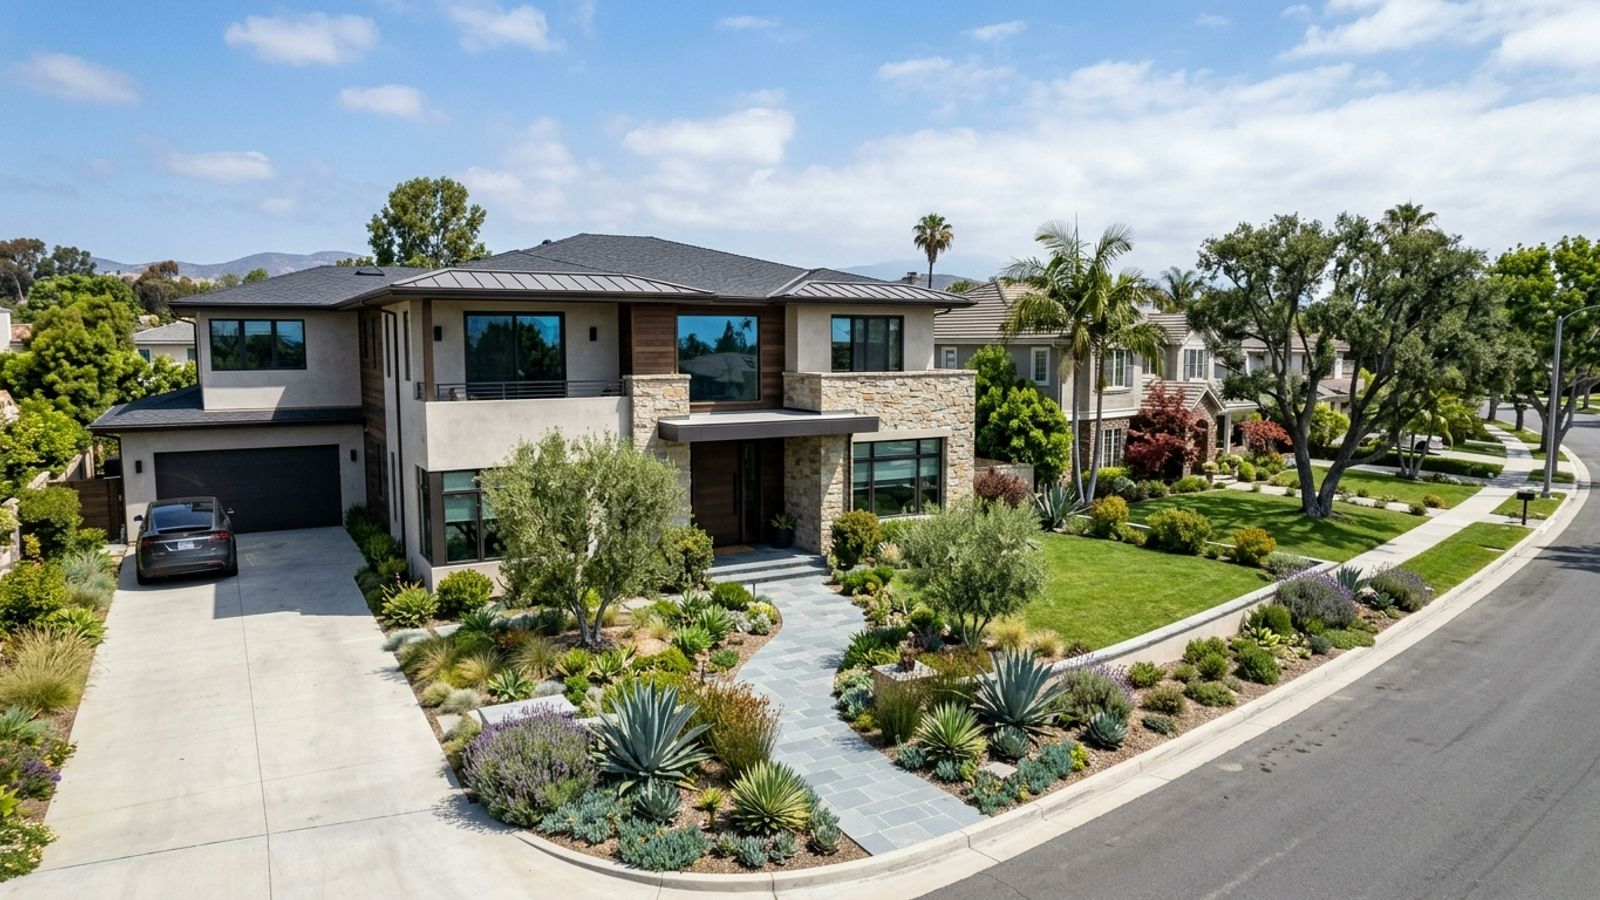
The median home price in Orange County, CA currently sits around $1.22 million. At that price point, the interest rate on your loan shapes your monthly payment just as much as the purchase price itself. This is especially true for first-time home buyers in Orange County, CA.
Whether you're buying your first house or selling a long-time family property, financing costs dictate how the local market moves. Buyers need to know how to structure their financing, and sellers need to understand how those same borrowing costs affect demand for their listings.
Where to Find Current Mortgage Rates in Orange County
Mortgage rates change constantly throughout the trading day. Lenders adjust their pricing based on bond market movements, inflation data, and broader economic indicators - which means searching for a single static rate online won't give you an accurate picture of what you'll pay. The rate you see advertised on a national portal at breakfast might look completely different by the time you submit an application that afternoon.
Getting Your Actual Rate Quote
To see exactly what it costs to borrow money right now, you need a same-day quote from a lender. When you apply, the lender provides a formal Loan Estimate detailing your specific interest rate, closing costs, and monthly payment. This document accounts for your unique financial profile, the property type, and the exact loan product you choose. Until you have a Loan Estimate in hand, any number you see online is just an educated guess.
Why Rates Fluctuate Daily
Mortgage rates don't move in lockstep with the Federal Reserve's benchmark rate, though Fed policy influences them. Instead, most 30-year fixed mortgages track the yield on 10-year Treasury bonds. When investors anticipate higher inflation, bond yields go up, and mortgage rates follow.
Local factors don't dictate these baseline daily movements - but your specific geographic location and property type will affect the final pricing adjustments a lender applies to your loan.
How Mortgage Rates Affect Your Buying Power
A shift in borrowing costs changes what you can afford to buy in Orange County. When rates move up, your purchasing power drops, and you have to look at lower-priced homes to keep the same monthly payment. Understanding the math before you start touring properties is the only way to set a budget that holds.
With local homes spending roughly 43 days on the market, you do have a window to evaluate your options - but financing constraints will still drive the final decision.
Monthly Payment Comparisons
Consider an illustrative example using the current Orange County median sale price of roughly $1.22 million. Put 20% down and you're financing about $976,000.
For illustration only: at a 6% interest rate, the principal and interest payment on that loan is about $5,851 per month. At 7%, that same loan jumps to $6,493. Those figures exclude property taxes and insurance, which will add to your total housing cost.
The Price Versus Rate Trade-Off
That $642 monthly difference is why buyers often have to adjust their search criteria when borrowing costs shift. To hold the $5,851 payment at a 7% rate, you'd need to reduce your loan amount by roughly $95,000.
So you're weighing a smaller home at a higher rate against the risk that waiting for better conditions means higher prices. Waiting carries real cost - if values continue to appreciate, any savings from a lower rate can get wiped out entirely.
Loan Types That Influence Your Interest Rate
The mortgage product you choose sets the baseline rate the lender offers. Different loan structures carry different levels of risk for the bank, and they price that risk into your monthly payment.
Buyers in Orange County typically choose between fixed and adjustable structures, as well as various government-backed or conventional programs.
Fixed-Rate Versus Adjustable-Rate Mortgages
A 30-year fixed-rate mortgage locks in your interest rate for the life of the loan. Payments are predictable, though the initial rate is often higher than short-term alternatives. A 15-year fixed loan usually carries a lower rate, but the compressed repayment schedule means your monthly payments will be noticeably higher.
An adjustable-rate mortgage (ARM) typically starts with a lower introductory rate for a set period - five or seven years is common. After that initial term, the rate adjusts annually based on market conditions, so your payment can go up or down over time.
Conventional, FHA, and VA Loans
Conventional loans are the most common financing tool in Orange County and generally offer competitive rates for buyers with strong credit profiles. Because they're not insured by the federal government, lenders rely on your financial history to set the rate.
Government-backed options like FHA and VA loans often feature lower baseline interest rates than conventional products. VA loans, available to eligible military service members and veterans, frequently offer some of the most favorable terms on the market.
Ways to Secure a Better Mortgage Rate
You can't control the bond market, but you can control your personal financial profile. Lenders reserve their best pricing for borrowers who present the lowest risk of default - and even a fraction of a percentage point saves thousands of dollars over the life of a loan.
Improving Your Credit Score
Your credit score is the single biggest personal factor in determining your mortgage rate. Borrowers with scores above 740 generally qualify for the most favorable pricing tiers. Drop below that threshold and the lender will likely add adjustments that increase your rate. Review your credit reports for errors and pay down revolving debt before you seek pre-approval.
Down Payments and Discount Points
A larger down payment reduces the lender's risk and can result in a lower rate. Putting down 20% or more also eliminates the need for private mortgage insurance, which brings your total monthly housing cost down further.
You also have the option to buy down your rate by purchasing discount points at closing. One point typically costs 1% of your loan amount and lowers your interest rate by roughly 0.25%, though the exact math varies by lender.
Locking In Your Rate
Once you have an accepted offer, you can request a mortgage rate lock - an agreement that guarantees your interest rate for a specific timeframe, usually 30 to 60 days, protecting you if market rates rise before you close.
If your closing is delayed beyond the lock period, you may have to pay an extension fee to keep the agreed-upon rate. Confirm the expiration date of your rate lock with your loan officer during the escrow process. It's a detail that's easy to overlook and expensive to ignore.
Choosing a Local Mortgage Lender in Orange County
The company funding your loan impacts your transaction just as much as the rate they offer. A smooth escrow process requires a responsive lending team that knows this market.
Buyers have options ranging from large national institutions to small neighborhood brokerages, and knowing the differences helps you find the right fit.
Why Local Expertise Matters
Local mortgage lenders in Orange County operate in the same time zone as your agent and the escrow company. When something urgent comes up on a Friday afternoon, a local loan officer is far easier to reach than a national call center.
Local professionals also understand regional property types - the specific condo associations and homeowner associations common in Southern California, for instance. That familiarity tends to prevent underwriting delays that can put your purchase contract at risk.
Comparing Lender Types
Retail banks and credit unions lend their own money and offer their specific suite of loan products. If you already have a relationship with a local credit union, they might offer relationship-pricing discounts on your mortgage.
Mortgage brokers don't lend their own money - they shop your application across multiple wholesale lenders to find favorable terms. Direct lenders operate similarly to banks but focus exclusively on home loans, often processing and underwriting everything in-house for faster turnaround times.
What Rate Trends Mean for Orange County Home Sellers
Borrowing costs dictate how many buyers can afford to bid on your property. When rates rise quickly, the pool of qualified buyers shrinks, which tends to mean fewer showings and longer market times.
That said, housing inventory in Orange County remains low relative to demand. Recent data shows roughly 6,098 available homes, leaving the area with about 3.4 months of supply.
Understanding Buyer Demand
With supply levels below the four to six months considered a balanced market, buyer competition stays steady. Even when borrowing costs squeeze affordability, the lack of available homes supports property values.
Price your home based on recent comparable sales, not aspirational numbers. Buyers are working within hard payment limits, and an overpriced home will sit regardless of how tight inventory is.
Timing Your Listing
Trying to time your listing around interest rate predictions is a risky strategy. Pushing your timeline back in hopes that rates will drop might just mean you're competing with every other seller who had the same idea.
Focus instead on preparing your property to show well and pricing it accurately for current conditions. A well-presented home in Orange County will attract qualified buyers in almost any rate environment.
Mortgage Rate FAQs
What are mortgage rates today in Orange County, CA?
Mortgage rates change daily and vary based on your specific financial profile. To get an accurate current rate, you need to request a formal Loan Estimate from a lender. Online averages are only estimates and don't reflect the exact pricing you'll receive.
Should I wait for rates to drop before buying a home in Orange County?
Waiting for lower borrowing costs carries the risk that home prices will continue to rise in the meantime. The median sale price in Orange County is approximately $1.22 million, and persistent low inventory continues to fuel competition. Base your timeline on your personal budget rather than market predictions.
How do I get the best mortgage rate as a buyer in Orange County?
Improve your credit score, save for a larger down payment, and shop your application across multiple lenders. Borrowers with credit scores above 740 generally see the most favorable terms. You can also lower your rate by purchasing discount points at closing.
How much does a 1% difference in mortgage rate cost me on an average Orange County home?
On a $976,000 loan - a 20% down payment on a roughly $1.22 million home - a 1% rate increase changes the monthly principal and interest payment by about $642. Over a 30-year term, that single percentage point adds hundreds of thousands of dollars in total interest costs.
What credit score do I need to qualify for the most competitive mortgage rates in Orange County, CA?
Most lenders reserve their top pricing tiers for borrowers with a credit score of 740 or higher. You can secure financing with a lower score, but the lender will likely apply pricing adjustments that increase your interest rate.
How do current mortgage rate trends affect my home's selling price in Orange County?
Higher borrowing costs limit how much buyers can afford to pay, which can soften aggressive bidding wars. Orange County currently has about 3.4 months of housing supply, though, which keeps the market competitive. That low inventory helps support strong selling prices even when rates fluctuate.
Getting Local Guidance for Your Next Move
Real estate transactions require coordination between your agent, your lender, and the escrow company. Talking with a local real estate professional early in the process helps you map out a clear strategy before you start touring homes or preparing a listing.
A knowledgeable agent can connect you with trusted local lenders who have a proven track record of closing loans on time in Orange County. A conversation costs nothing and gives you a much clearer picture of where you stand.
Categories
Recent Posts